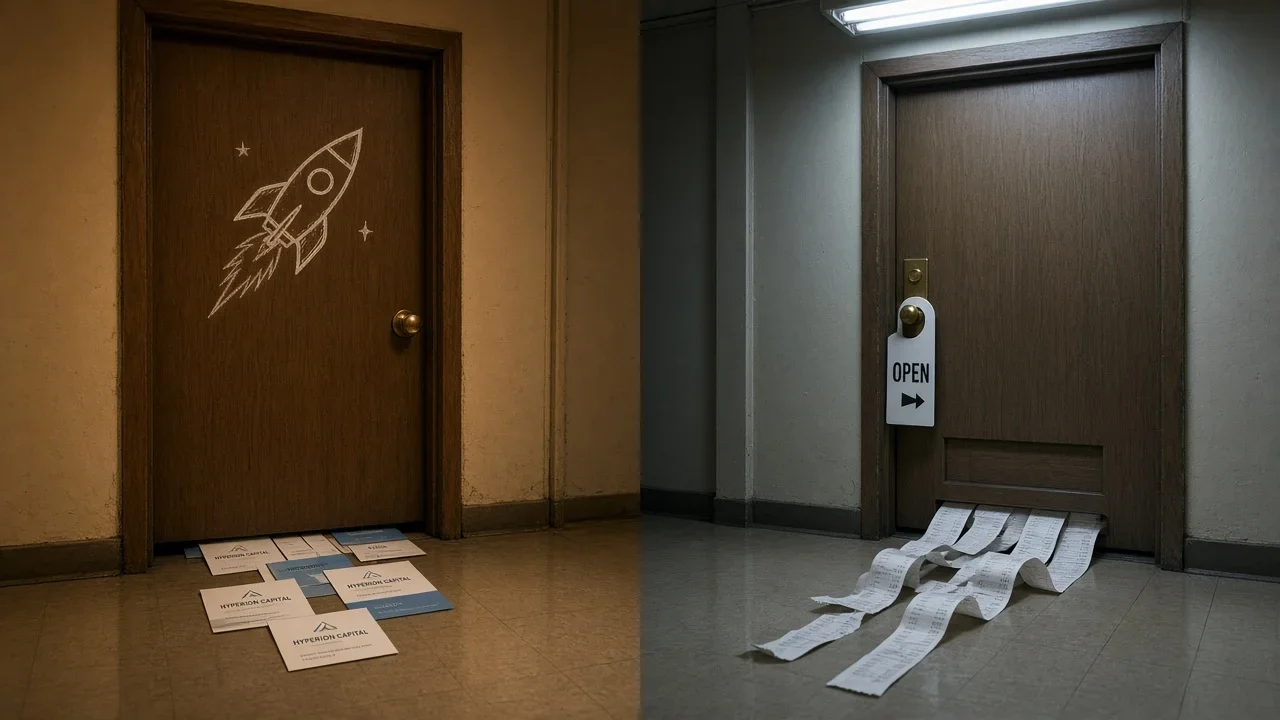
Tim Ferriss frames an underexamined entrepreneurial choice: build an equity-driven startup that swings for a very large outcome, or create a cash-flow business that supports a preferred way of living. The discussion is useful because it acknowledges that company design and life design are connected. A founder should understand that venture backing and bootstrapping bring different expectations, time horizons, and definitions of success.
The binary still begins too late. "Startup" and "cash-flow business" describe financing and outcome patterns, not the underlying customer problem or operating system. Choosing an identity before understanding those mechanics can make a founder force the business into a model it cannot support.
A venture-backed company is not free from cash flow; it temporarily finances negative cash flow in pursuit of a larger future asset. A bootstrapped company is not necessarily small, slow, or lifestyle-friendly. Inventory, long payment terms, regulated development, and enterprise sales can consume cash even when the owner rejects venture capital. Software with recurring revenue can grow quickly from customer funding. The important distinction is not which door carries the more appealing label, but when cash leaves, when it returns, and what obligations bridge the gap.
The lifestyle side can be misleading for the same reason. Systems and delegation may reduce a founder's operational involvement, but work does not disappear when the owner becomes less central. It moves to employees, contractors, suppliers, platforms, or customers. A business that creates freedom for its founder through fragile jobs, underpriced support, or hidden platform dependence has optimized one person's lifestyle rather than designed a resilient enterprise.
Venture scale has its own hidden transfers. Outside capital can fund research, distribution, and infrastructure that customer revenue cannot yet support. It also commits the company to an outcome large enough and fast enough to satisfy investors. The founder may retain substantial paper value while losing the practical ability to choose dividends, pace, market, or a modest acquisition. Equity and cash flow are therefore not competing rewards; they are claims held by different parties at different times.
Nor must the choice remain permanent. A service can finance the discovery of a product. A bootstrapped product can later raise capital when a repeatable opportunity appears. A venture-backed company may narrow toward profitability after the original growth theory fails. Hybrid paths create tensions—service clients can distract a product team, and new investors can change priorities—but ruling them out for identity's sake is not discipline.
The better first questions are operational and personal. What problem is valuable enough that customers will pay to solve it? How much capital is required before credible proof? Is growth constrained by software, labor, inventory, regulation, or distribution? Which decisions must the founder preserve? What income, time, health, and family constraints are non-negotiable? Who bears the downside if the experiment fails? Only then can financing be matched to the business rather than used to define it.
The addendum is that "startup or cash-flow business" is the wrong first question. It invites founders to choose between a rocket and a shop before they know what must be transported, how far, and at whose risk. Design the sequence of evidence, cash, control, and responsibility first. The right company may be venture-backed, bootstrapped, or change between them. Success is not loyalty to a category; it is building an arrangement in which the economics and the founder's desired life can remain true at the same time.